AI Answering Service for Mortgage: Who Picks Up After Hours
The calls your floor misses are the ones a competitor answers. An AI answering service for mortgage closes that gap only if it does less than the vendors promise. It takes a few details, books a time, and gets the borrower to a licensed loan officer. Anything more starts to look like loan origination.
What an AI answering service for mortgage should do on the call
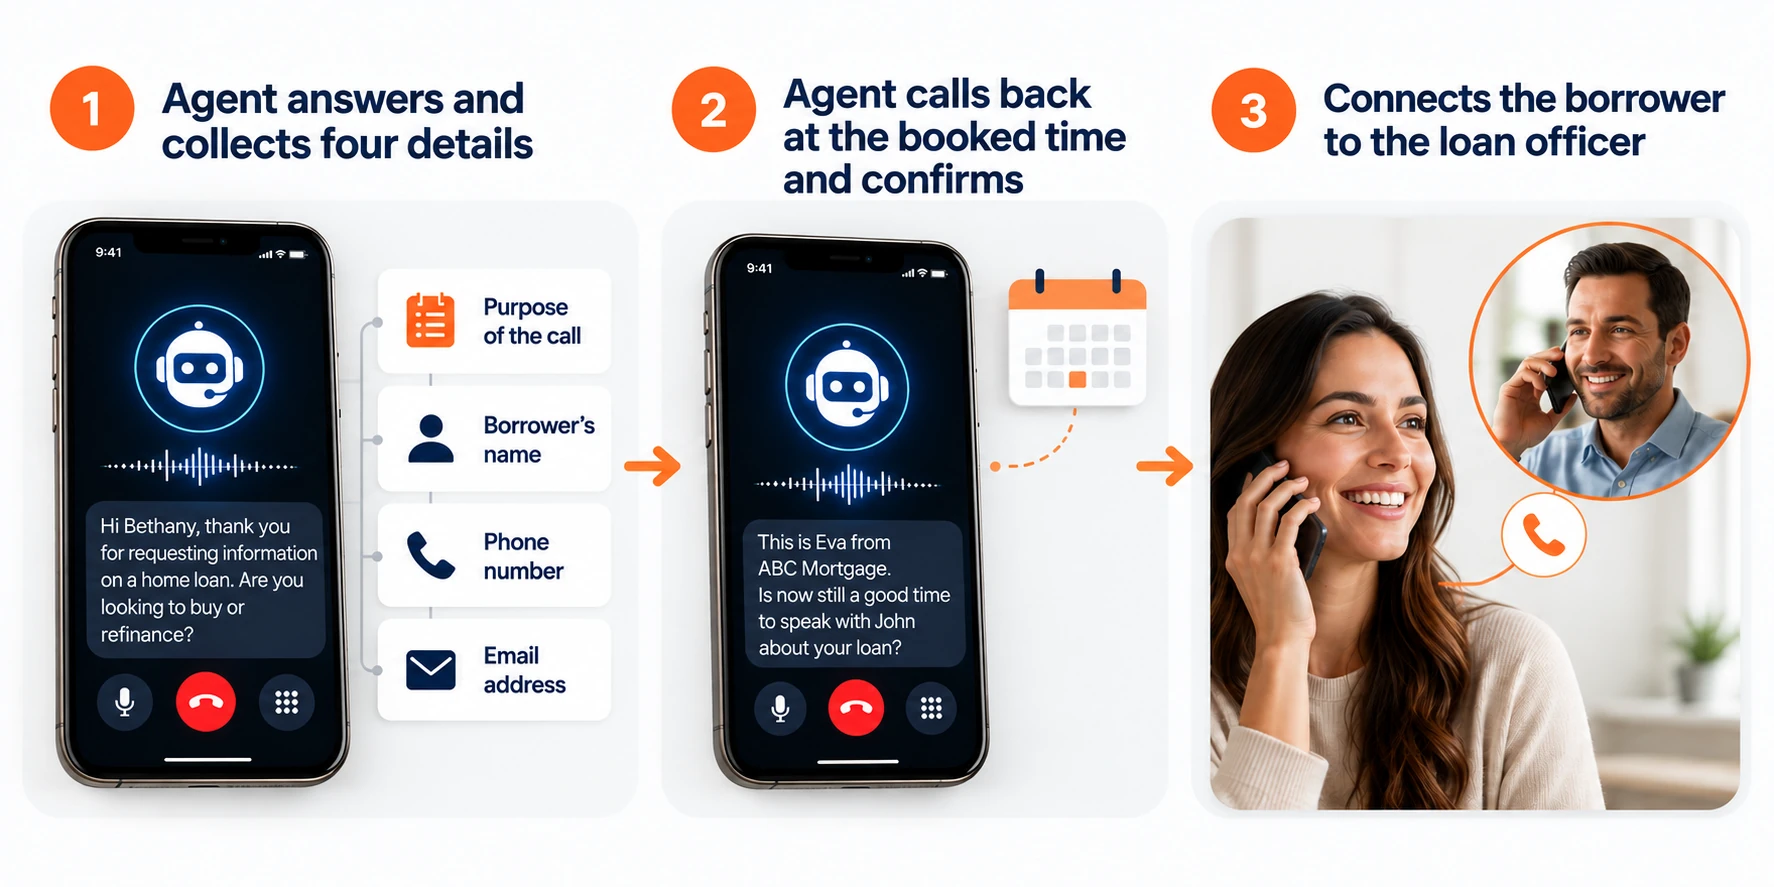
Keep the job small. When nobody on the floor can take the call, the agent collects four things:
- The purpose of the call
- The borrower’s name
- Their phone number
- Their email
Then it books a callback at a time the borrower picks. That is the whole call. A short call is a feature here. The borrower called to reach a person, and the agent’s job is to make that happen fast.
Answering inbound calls is one AI job among several in our list of AI software for loan officers.
What it must not say
An AI answering service should not quote rates, discuss loan terms, or take an application. Under Regulation H, taking an application and offering or negotiating terms are what define a mortgage loan originator. Those activities require a licensed person.
How that rule applies to software is a question for your counsel. The safe design keeps the agent well short of the line. Shape’s agent does not discuss rates or do anything that would require a licensed mortgage professional. When a borrower asks for a rate, the right answer is that the loan officer covers it on the callback.
The callback is where the loan gets made
Answering is half the job. At the booked time, the agent calls the borrower back. It confirms the time still works, then connects the borrower to the loan officer. The loan officer picks up a borrower who expects the call and has already said why they want it.
Without that step, an answering service just moves voicemail into a new box. Someone still has to remember to call back, and the borrower has usually moved on by then.
The callback carries a compliance question. In 2024 the FCC ruled that AI-generated voices are “artificial” under the TCPA. Calls using an artificial voice need the consumer’s prior express consent. The borrower agreed to the callback time on the first call. Whether that counts as consent for an AI-voiced callback is your counsel’s call. The answer may vary by state.
After hours lead answering is only half the coverage
Evenings and weekends get the attention. Overflow during business hours costs as much. A rate move or a mail drop sends a spike of calls no floor can absorb.
The same agent covers both. During the day, it transfers the caller into the call queue. If no loan officer frees up, it books the callback. After hours, it books the callback. Either way, the borrower reaches a person instead of a recording.
Some teams solve coverage with people instead, which is a real trade-off. That decision comes down to whether to automate qualification or hire an ISA. Automated qualification, such as qualifying leads by voice, is outbound work with different rules than answering inbound.
An AI receptionist for mortgage brokers versus a native agent
Most products on this search are standalone receptionists. They answer well and hand you a transcript, an email or a webhook. Someone then has to match it to a lead, assign it and schedule the callback in another system.
A native agent works inside the CRM. The details it collects land on the borrower’s record. The callback books on the assigned loan officer’s calendar. The transfer goes to the queue the routing rules already use. Nothing gets copied between systems, so nothing gets lost there. That is the difference between answering inside the best mortgage CRM system and bolting a receptionist on.
How to measure AI phone answering for loan officers
Track four numbers for any AI answering service for mortgage, in hours and out of hours:
- Answer rate. Share of inbound calls that reached a person or the agent.
- Callback completion rate. Share of booked callbacks where the borrower answered at the agreed time.
- Connect rate. Share of completed callbacks that reached a loan officer.
- Funded rate. Funded loans from agent-answered calls, against calls a person answered first.
The last comparison tells you what the agent is worth. If agent-answered calls fund close to the rate of live answers, coverage pays. If they fund far below, look at the callback timing before blaming the agent.
The same numbers show where texting fits. Some borrowers who miss a callback will reply to a text. That is the ground covered by AI SMS for mortgage lead qualification.
Frequently asked questions
Does an AI answering service replace a loan officer assistant?+
No. The agent covers the phone when nobody can, and books the callback. A loan officer assistant works files: documents, conditions, follow-up with processing. The two jobs overlap only at the phone. Adding an agent takes the after-hours and overflow calls off the assistant’s plate.
What should a mortgage team check before turning on AI answering?+
Five things. Which calls route to the agent, and when. Where a live transfer goes during business hours. What the agent says when asked about rates. Whether callback times stay inside permitted calling hours. And whether your counsel has reviewed how the callback consent is captured.