Most lists of the best CRM for banks and credit unions are general mortgage CRM lists. Each entry gets a sentence about members added to it.
That misses what actually separates these platforms for a depository. Your mortgage division runs like any mortgage shop, so the mortgage capability has to be real. But you also hold a relationship the borrower already has. Almost nothing in the category is built to use it.
So the best mortgage CRM for banks and credit unions is the one that does both. Six platforms below, what each is best for, and where each falls short.
How to choose the best mortgage CRM for banks and credit unions
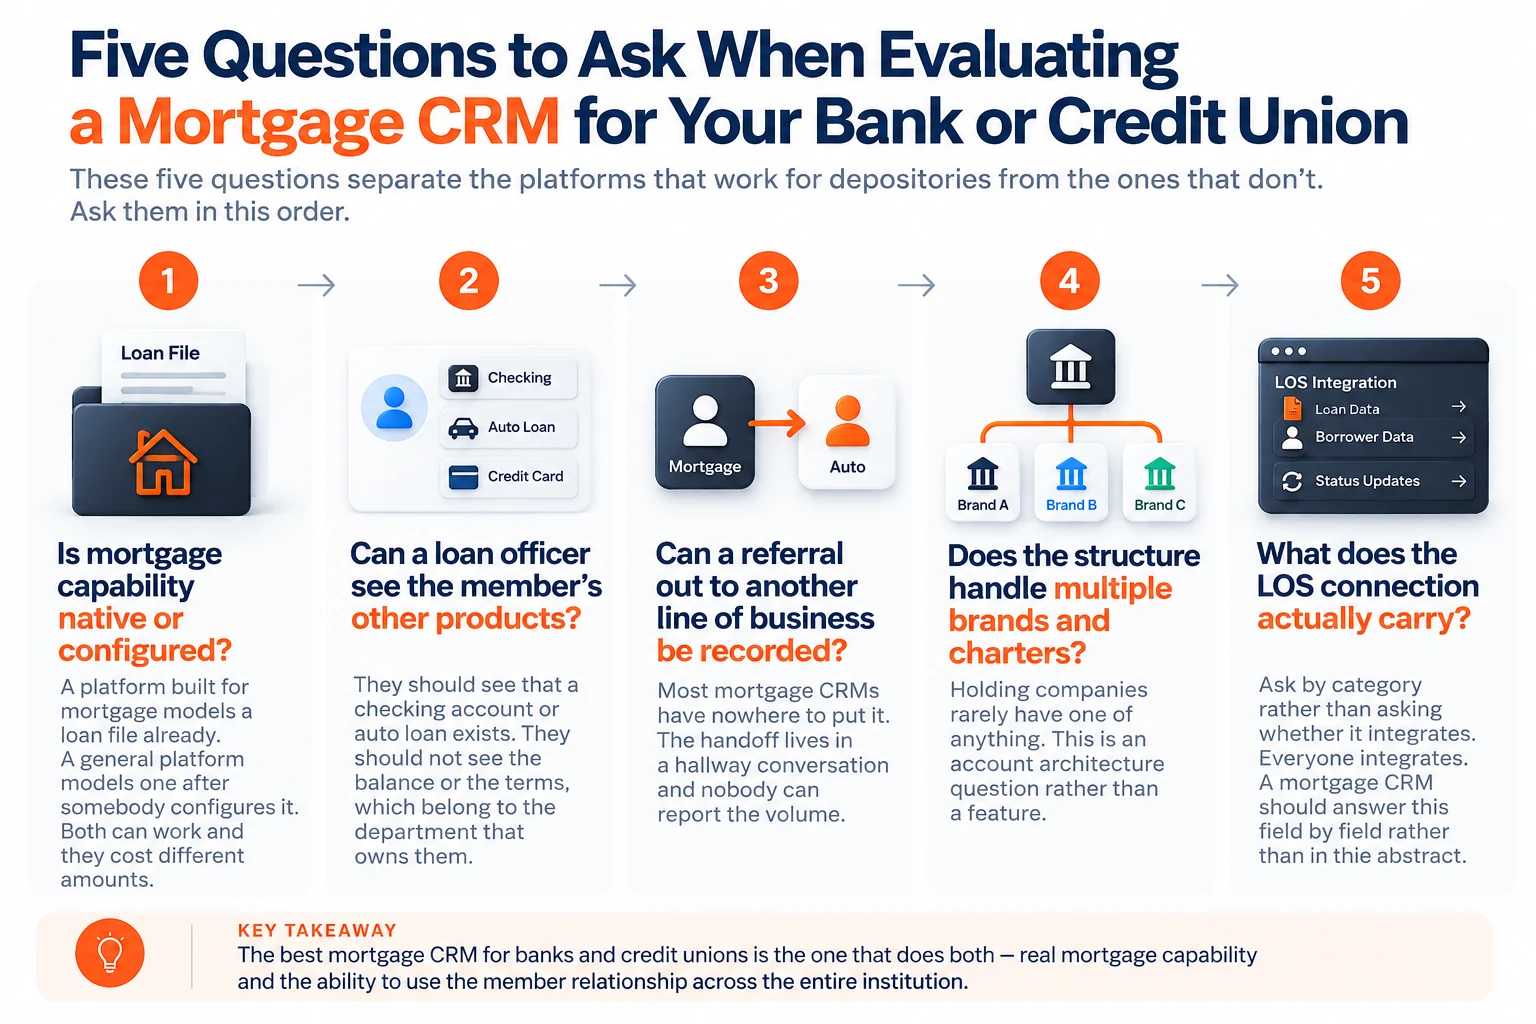
Five questions separate these platforms for a depository. Most comparison lists ask none of them.
Is mortgage capability native or configured? A platform built for mortgage models a loan file already. A general platform models one after somebody configures it. Both can work and they cost different amounts.
Can a loan officer see the member’s other products? They should see that a checking account or auto loan exists. They should not see the balance or the terms, which belong to the department that owns them.
Can a referral out to another line of business be recorded? Most mortgage CRMs have nowhere to put it. The handoff lives in a hallway conversation and nobody can report the volume.
Does the structure handle multiple brands and charters? Holding companies rarely have one of anything. This is an account architecture question rather than a feature. The same ground for lenders with separated books is in running one CRM across branches.
What does the LOS connection actually carry? Ask by category rather than asking whether it integrates. Everyone integrates. A CRM for mortgage lenders should answer that question field by field rather than in the abstract.
Quick comparison
Platform
Best for
Mortgage capability
Institution-wide
Shape
A mortgage division that wants a mortgage system
Native
Partial
Total Expert
Outreach and customer intelligence across a large database
Native
Partial
Insellerate
Institutions running several lending lines across channels
Native
Partial
Creatio
Institutions wanting one configurable platform across products
Configured
Yes
Salesforce FSC
Institutions with an IT function that want to build
Configured
Yes
HubSpot
Marketing-led teams with integration budget
Built by an agency
Partial
1. Shape
A mortgage CRM for the mortgage division, with a defined view into the wider relationship.
Roughly 1,500 standard fields carry the full MISMO 3.4 set. A loan file does not get built out of custom fields. LOS connections run by API with Encompass, LendingPad, LendingDox and Byte. SOC 2, HIPAA and PCI certified.
Best for: a mortgage division at any size, wanting mortgage-native capability plus a record of the wider relationship.
Pros
Mortgage data model out of the box rather than configured into one
Product-existence visibility, with referrals to other lines tracked separately from the loan
Multi-brand structure that runs from one branch to a multi-charter group
Cons
Not a core banking platform, so deposits and cards stay on their own system
The borrower-facing portal is a separately priced add-on rather than part of the core platform
The relationship view depends on what your core or data warehouse can expose
2. Total Expert
A long-standing option at large depositories, built around customer intelligence rather than sales-floor workflow.
Total Expert describes itself as purpose-built for banks, credit unions and lenders, with more than 200 financial institutions using it. Its Customer Intelligence layer monitors contacts for equity thresholds, listings, rate opportunities and credit inquiries by other lenders. Encompass and Empower integration is deep, and third-party comparisons consistently name it as an enterprise option.
Best for: an institution whose priority is database-wide engagement signals rather than pipeline workflow.
Pros
Built for financial institutions rather than adapted to them
Customer Intelligence signals are genuinely useful for retention
Works alongside Salesforce rather than requiring a choice
Cons
Heavier than a small division needs, and priced accordingly
Marketing and engagement depth exceeds its sales-floor workflow depth
Third-party comparisons place it above roughly twenty originators
3. Insellerate
The strongest fit if mortgage is one of several lending lines you run.
Insellerate supports mortgage, auto, personal, consumer and commercial products across retail, consumer-direct, wholesale, branch, dealer, contact center and digital channels. That multi-product, multi-channel structure maps unusually well onto a depository, where mortgage sits beside other lending. The company cites more than 1,300 APIs for connecting legacy systems. Its Aithena AI layer covers lead scoring, conversation intelligence and quality assurance.
Best for: institutions running mortgage alongside auto, personal or commercial lending, especially with a contact center.
Pros
Multi-line-of-business by design rather than by configuration
Broad connectivity to legacy core and servicing systems
Conversation analysis across interactions rather than sampled call review
Cons
Leans toward high-volume distribution and sales-floor discipline
Less natural for a small relationship-led division
Published performance figures come from named customers without stated methodology
4. Creatio
The option when the institution, not the mortgage division, is buying.
Creatio runs a dedicated financial services vertical on a no-code platform. Pre-built workflows cover deposit accounts, lending, cards, mortgages, wealth and insurance. Named US institution customers include Ent Credit Union, Jersey Shore Federal Credit Union and Lake City Bank. A partner publishes a Symitar connector on the Creatio marketplace, which matters if you run Jack Henry.
Best for: institutions wanting one configurable platform across deposits, lending and service.
Pros
Genuine institution-wide scope rather than mortgage with extras
No-code configuration reduces dependence on developers
Core banking connectors exist for common credit union cores
Cons
Mortgage capability is a configured workflow rather than a mortgage-native product
Configuration effort is real even without code
A mortgage division buying alone will find it heavier than it needs
5. Salesforce Financial Services Cloud
Powerful, extensible, and it expects you to bring an IT function.
Financial Services Cloud gives institutions a data model for financial relationships. Its ecosystem is large enough that most vendors integrate with it rather than compete. Total Expert, among others, surfaces its own signals inside Salesforce workflows. Comparison guides in this category consistently qualify Salesforce as the choice for institutions with an IT department.
Best for: institutions with in-house admin and development capacity that want to build exactly what they want.
Pros
Extensible to almost any requirement
Large partner and integration ecosystem
Already in place at many institutions for other lines
Cons
Nothing mortgage-specific arrives configured
Needs ongoing admin and development resource
Total cost of ownership is easy to underestimate at purchase
6. HubSpot
Excellent marketing software that becomes a banking CRM only after somebody builds it.
HubSpot brings strong campaign tooling, usable reporting and enterprise-grade controls including SOC 2 Type II and granular permissions. The depository implementations that exist are built by agencies. They construct bi-directional integrations to core and LOS platforms such as Fiserv, FIS, Symitar and Encompass. That is a real route and it is a build rather than a purchase.
Best for: marketing-led institutions with budget for an integration partner.
Pros
Best-in-class marketing automation and usability
Strong permissions and audit controls
Adoption is rarely the problem
Cons
No mortgage data model, and no loan file concept
Core and LOS connectivity is a custom build with ongoing maintenance
The cost that matters is the integration, not the license
What this means in practice
Sort the six into three groups and the decision gets shorter.
Mortgage-native platforms are Shape, Total Expert and Insellerate. If your mortgage division is buying for itself, the answer is almost certainly in that group. The choice between them is about scale and how many lending lines you run.
None of the three is a core banking platform, and none is trying to be. Deposits, cards and service stay where they are. What differs is how much of the wider relationship each will surface, and what it takes to get it there.
Institution-wide platforms are Creatio and Salesforce. If the institution is buying one system for deposits, lending and service, that is where to look. The mortgage team should test the loan file model hard before agreeing.
HubSpot is a different decision. It is a build, and it should be priced as one.
Whichever way you go, work through which mortgage CRM fits a loan officer as well. Most of what matters to your mortgage team is what matters to any mortgage team. A shortlist has to satisfy both sets of requirements rather than either alone.
Frequently asked questions
Do banks and credit unions need a different mortgage CRM from an independent lender?+Mostly no. Mortgage runs as its own division at most depositories, so the pipeline, LOS integration and follow-up requirements are the same. What differs is visibility into the customer’s other products and the ability to record a referral out to another department. Evaluate mortgage capability first, then check those two things.
Should mortgage live inside our main banking CRM?+Usually not. A mortgage pipeline has stages, milestones, expiry dates and a regulatory file with no equivalent on the deposit side. A general banking CRM carrying all of it serves neither team well. A mortgage system with a defined view into the wider relationship is the arrangement that holds up.
What should a loan officer see about a member’s other accounts?+That the products exist, and nothing more. Knowing a member holds an auto loan gives the officer a reason to refer them. Balances, rates and terms belong to the department that owns the product. Set the boundary deliberately, because unwinding it after a compliance review is harder.
How much does a mortgage CRM for a bank or credit union cost?+Most vendors in this category quote on request rather than publishing rates. The figures that circulate publicly rarely match what institutions pay. Ask for total cost of ownership including implementation, integration and ongoing administration. The license is usually the smallest line.
Can these platforms connect to our core banking system?+It varies and it is worth asking early. Creatio has marketplace connectors for common credit union cores. HubSpot implementations build the connection. A mortgage CRM for credit unions or banks connects to your LOS rather than your core. That is usually the right boundary for a mortgage division.
Kevin Benner is the Chief Revenue Officer at Shape Software, where he leads revenue, marketing, and customer growth. He brings over 23 years of experience in mortgage lead generation and sales technology.
Mortgage texting software is judged by what happens after the borrower replies, not by how many texts it can send. Any tool can send. The ones worth paying for put the reply on the borrower’s record and stop the automation. Then they show a loan officer who needs an answer. Everything else is a bulk […]
Most lenders reading about the Encompass SDK transition deadline have nothing to migrate. That is not what the coverage suggests. The subject has produced a steady run of posts about an Encompass SDK sunset, an end-of-life, a cutover. Several carry a countdown clock. Some of it is written by firms that sell migration work. Here […]
Recruiting conversations spend all their technology time on one question, which is what platform the producer will be on. That is rarely the expensive part. The expensive part is everything those systems render, and the reason nobody plans for it is that no system moved. A branch transition checklist that only lists platforms will miss […]