Choosing a Mortgage Marketing Agency: 6 Full-Service Firms Compared
The right mortgage marketing agency runs your marketing and leaves you owning everything it builds. Most lists of mortgage marketing agencies are written by an agency that ranks itself first. Shape builds mortgage CRM software and sells no agency services. None of these firms is ours, and none paid to be here.
This guide compares six full-service agencies: what each one runs, who it fits and the catch. It then covers what to own before you sign and the contract terms that trap lenders. It ends with when to skip the agency.
What counts as a full-service mortgage marketing agency
A full-service agency runs strategy, paid media, SEO, content and creative under one contract. It owns the plan and the execution. You own the results and the assets.
Search for mortgage marketing companies and three other kinds of business come back. They are not on this list:
- Website and landing page shops. They build the site. Some add SEO or ads as extras.
- Lead sellers. They sell the borrower, not the marketing.
- Software. CRM, funnel and email tools your team runs itself.
A website-first firm can be the right hire. It is a different hire, judged on different terms.
The 6 best mortgage marketing agencies, compared
Every fact below comes from the agency’s own website, checked October 22 2026. The order reflects mortgage focus and scope, not results we can verify. Performance figures the agencies publish about themselves are left out. None states a sample or a method.
| Agency | What it runs | Who it fits | Published pricing |
|---|---|---|---|
| Mortgage Broker Marketing | Websites, SEO, paid ads, email and text, reputation | Brokers and small mortgage companies | None |
| Kaleidico | Websites, SEO, content, paid search, email, lead gen | Lenders and larger brokerages | Budget ranges on its intake form |
| William Mills Agency | Financial PR, content, social, crisis communications | Lenders and executives who need press | None |
| NexLevel Advisors | Fractional CMO plus execution | Lenders without a senior marketing leader | None |
| Simplicity Media | TV, CTV, radio, paid search, paid social | National and direct-to-consumer lenders | None |
| Digital Strike | SEO, paid search, social, web, email | Regional lenders that want SEO depth | None |
1. Mortgage Broker Marketing
Mortgage Broker Marketing builds mortgage websites and then drives the traffic to them. Its service list covers SEO and Google Business Profile, Google and Facebook ads, and retargeting. It also runs email and text to past clients, review requests, and call tracking. Training videos and guides come with it. The San Diego firm is mortgage-only, led by CEO Brian Frantz. It is the most direct fit here for a marketing agency for mortgage brokers.
Who it fits: brokers and small mortgage companies that want one vendor for the site and the traffic.
The catch: the website is the center of the program. Its pages don’t say who owns the site or the domain. Get that answer in writing before you sign.
2. Kaleidico
Kaleidico says it has tested mortgage marketing strategies since 2005. Mortgage is the first of its three verticals, next to law firms and senior living. The mortgage program bundles a website, SEO and content, paid search, email and landing page work. It starts with a 90-day plan and includes help with sales follow-up. Kaleidico also offers leads on a per-lead basis.
Who it fits: lenders and larger brokerages that want a mortgage-specific team running the whole funnel.
The catch: budget and definitions. Its intake form asks for a budget in ranges from under $5,000 to $30,000 and up. It says its programs generate exclusive leads but doesn’t define exclusive. Ask whether leads sold per lead go to anyone else.
3. William Mills Agency
William Mills Agency is a public relations firm for the financial industry. It says it has served mortgage for more than thirty years. Services cover media relations, content, social, crisis communications and AI search. For mortgage company PR services, it is the only specialist on this list.
Who it fits: lenders and executives who want trade press, a crisis plan or a public voice.
The catch: PR builds reputation, not a lead pipeline. Its mortgage client types lean toward technology and service vendors: origination systems, appraisal software, servicing. A lender chasing applications would pair it with a performance agency.
4. NexLevel Advisors
NexLevel Advisors sells a fractional CMO. That means a senior marketing leader in your leadership meetings, plus the hands-on work. Scope runs from a few days a month to an embedded marketing department. It also manages a client’s existing team and agencies. Founder Michael Hammond describes thirty years in mortgage and fintech.
Who it fits: lenders with a real marketing budget and no senior marketing leader. It also fits shops paying agencies that nobody manages.
The catch: much of its published work is for mortgage technology vendors selling to lenders. That is a different job from selling loans to borrowers. Most engagements run at least 90 days.
5. Simplicity Media
Simplicity Media is a performance media buyer. It runs TV, connected TV, radio, podcast and Hispanic media, plus paid search and paid social. Creative and landing pages are priced separately. Its mortgage page cites CashCall Mortgage as past experience and offers funded-loan tracking. It names the rules it works under: TILA, RESPA, the MAP Rule, Fair Housing and TCPA.
Who it fits: national and direct-to-consumer lenders with a budget built for TV and radio.
The catch: this is brand-scale buying. A loan officer or a single branch has no use for a TV buy. It publishes no minimum.
6. Digital Strike
Digital Strike is a generalist agency in St. Louis. It lists 20 industries, and mortgage lender marketing is one of them. The mortgage offer covers SEO, local SEO, paid search, social, content, email, display and landing pages. It plans in 90-day cycles, with a new scope of work each quarter. Reporting pulls from Google Analytics, Google Ads and CRM data.
Who it fits: regional lenders and brokers that want deep SEO and paid search, with mortgage knowledge in-house.
The catch: it is not a mortgage specialist. Its mortgage page doesn’t address advertising compliance, so your own review carries all of it.
What to own before you sign
None of the six agencies publishes its prices. None says who owns the ad accounts, the website or the lead data. That doesn’t mean they keep them. It means you ask, and the answer goes in the contract.
| Asset | Why it matters | What to require |
|---|---|---|
| Ad accounts | Years of conversion history and audiences live there | Google Ads and Meta accounts in your business name. The agency gets user access |
| Domain and DNS | Whoever holds the registrar login controls your site and email | Registrar account in your name |
| Website and hosting | Rebuilding a site can cost months of rankings | Admin login, plus a full export when the contract ends |
| Tracking | Pixels, GA4 and Search Console hold your data history | Every property created under your accounts |
| Call tracking numbers | Agency-owned numbers stop ringing when you leave | Numbers ported to you on exit |
| Lead data | The borrower list is the asset you paid for | Leads delivered to your system, with the source tagged |
The last row decides the rest. Every lead an agency generates should land in a mortgage CRM tool you control, tagged by source and campaign. Then you can judge the agency on funded loans, not on its own report.
The list of what to set up before you spend is short. A Google Ads account, a Meta Business Manager, GA4 and conversion tracking, all in your business name. Build them first. Then add the agency as a user.
Contract terms that trap lenders
A bad agency contract is easy to sign and slow to leave. Check six terms before anyone starts work.
- Term length. Ninety days is a fair test. Two of the six describe 90-day cycles or minimums. A twelve-month lock with automatic renewal protects the agency, not you.
- Notice period. Thirty days is fair. Longer notice is a second lock.
- Setup fees. Find out what the fee builds and whether you own it when you leave.
- Ad spend. Spend should bill to your card, straight from Google or Meta. If it runs through the agency, ask for the markup in writing.
- Creative. Ads, copy, landing pages and photos should transfer to you on payment.
- Exit. Put the handover in writing: logins, files and exports, by a set date.
Then fix what gets reported. Clicks and leads are agency numbers. Applications and funded loans are yours. Ask for the second set from month one.
Compliance is still your license
The agency writes the ad. Your company name and NMLS number sit on it. An agency’s review process doesn’t move responsibility off you. Treat what follows as a checklist for your compliance team, not legal advice.
- Meta targeting. Mortgage ads run under Meta’s Special Ad Category. It removes ZIP code, gender and lookalike targeting and fixes age at 18 to 65+. An agency pitching narrow Meta targeting for mortgage is describing something Meta doesn’t allow.
- Trigger terms. Under Regulation Z, certain terms in an ad require added disclosures. A down payment or a payment amount is one.
- License disclosures. States set their own rules for NMLS IDs and license details in ads. Requirements may differ by state and by channel.
Ask each agency how its compliance review works, and who signs off. Then keep your own review before anything goes live.
Hire an agency, buy leads, or run it in-house
An agency pays off when three things are true. You can fund at least 90 days of fees and media. You have loan officers ready to work the leads fast. And no one in-house runs marketing at a senior level.
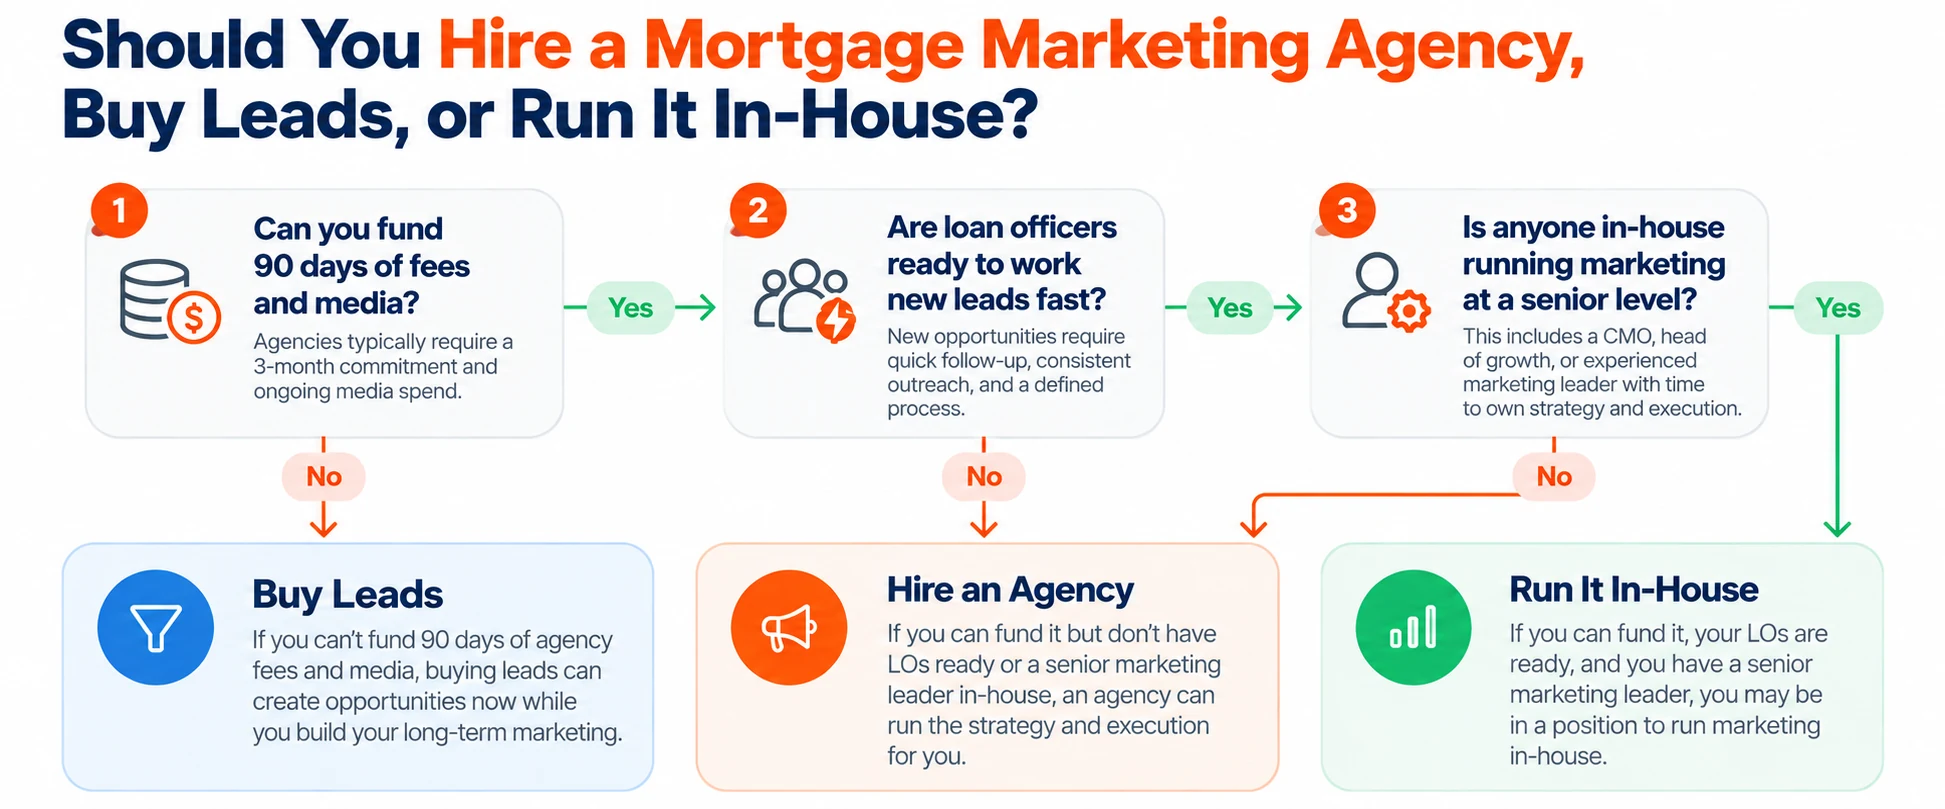
Bought leads are the faster path when you need applications this month. Compare vendors on where to buy mortgage leads, and price every source per funded loan.
A solo loan officer rarely needs a retainer. Past clients, referral partners and local search do more for that budget. Those plays are in the loan officer marketing playbook, and none of them needs an agency.
Whichever path you choose, the results depend on follow-up. An agency can fill the pipeline. It can’t call the borrower back in five minutes.