Caller Reputation for Mortgage Lenders: Why Calls Get Flagged
Your connect rate is falling and your dial count is climbing. The numbers still ring. Borrowers see “Spam Likely” and decline.
Most shops respond by buying more numbers or dialing harder. Both are the wrong move, and both are what the category keeps recommending. Caller reputation for mortgage lenders is scored on how your traffic behaves. It is not scored on how many numbers that traffic runs through. Spreading the same behavior across more lines spreads the problem with it. Four separate systems decide what a borrower sees when you call. Only one of them decides whether you get labeled, and it is not the one every vendor sells you.
Why connect rates drop when dials go up
Contact rates fall for a dozen reasons, and every one of them feeds the spam label. The label then pushes contact rates lower again. That loop is the whole problem.
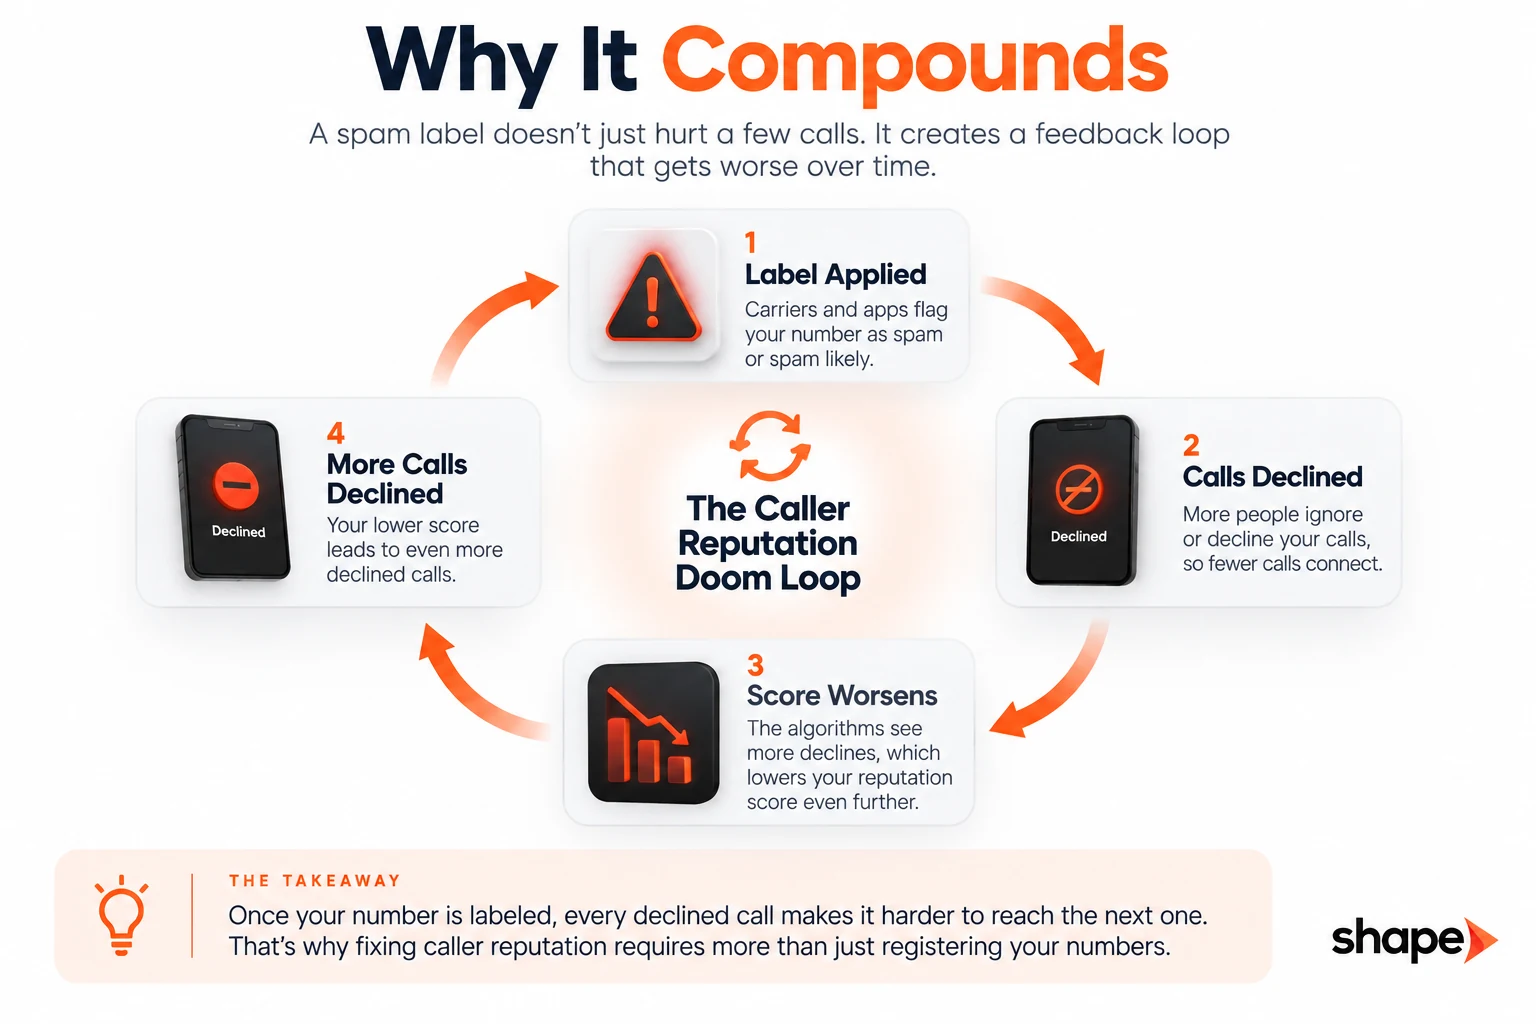
It runs like this. A borrower declines or lets it ring out. The engine reads that as an unwanted call. Short calls and repeat dials read the same way. The score drops and the label appears. More borrowers decline because of the label. The score drops again.
I have watched sales floors answer that slide with more volume. More dials per number feed the exact inputs that lowered the score. The connect rate falls faster. A shop that does nothing does not hold steady at a bad number either. It slides.
The starting point is already hard. In a July 2020 Pew Research Center survey of 10,211 U.S. adults, 80% said they generally do not answer cellphone calls from unknown numbers. Your borrower asked to hear from you. Your number is still unknown to them.
Getting out of the loop takes consistency, not volume. That means steady daily patterns, clean data and calls people want to stay on.
What feeds the cycle
Four inputs drive contact rate, and each one also feeds the score.
The number. A recycled number carries its last owner’s history. An unregistered number has no baseline. A flagged number gets declined on sight.
Timing. A call outside the borrower’s local hours gets ignored or reported. In some states it also runs into state calling-hour rules, so check them with your counsel.
The list. Disconnected and wrong numbers produce short, unanswered calls. The engine scores those against you. An old database pull or an aged purchased lead is the mortgage version of a bad list.
Dialing behavior. Parallel and multi-line dialing looks like automated traffic. So do bursts of calls after a lead buy, and repeat dials to one borrower in a day.
None of these is fixed by a new number. All four follow the shop to whatever line it dials from next.
Four systems get confused, and only one decides the label
They do different jobs and the industry uses the names interchangeably.
| System | What it does | Does it stop a spam label |
|---|---|---|
| CNAM | Shows a name on legacy caller ID lookup | No |
| STIR/SHAKEN | Signs the call so carriers can verify it is not spoofed | No |
| Branded Caller ID | Puts a verified name and logo on supported handsets | No |
| Spam analytics | Scores your traffic and applies the label | Yes, this is the one |
Signing a call proves you are who you say you are. It does not say anything about whether people want the call. A verified, branded, correctly attributed call can still be scored as a nuisance. Those are two different questions, and two different systems answer them. That is the sentence most lenders have never been told.
Who scores caller reputation for mortgage lenders
Three analytics engines do most of the phone number reputation scoring in the US market: Hiya, First Orion and TNS. Carriers and handset apps draw on them to decide what appears on screen. Public sources disagree about which engine sits behind which carrier, and the mappings change. Do not build a plan around one.
What matters operationally is simpler. Registering with one engine does not register you with all of them, so remediation means approaching each separately.
The engines do not score one number in one way. They score several dimensions at once and roll them into a single risk level. Some of those dimensions describe the number itself. Others describe how your calls behave once they are placed. Answer rate and call duration are scored inputs, not just results. That behavioral half is the part no registration can reach, and it is the part you control.
What gets a lender’s numbers flagged
Consistency is the biggest trigger. A number that dials lightly one day and floods the next looks like a different caller each day. Steady patterns build trust with the engines. Erratic ones spend it.
Six things feed the score, and a producing shop generates most of them without trying.
- High volume pushed through too few numbers, or volume that spikes and stops
- Low answer rates, which the model reads as unwanted calls
- Short call durations, including hang-ups and zero-duration attempts
- Complaints from recipients
- Recycled numbers carrying a previous owner’s reputation
- Unregistered or unattested traffic
The recycled-number point catches people. Every number you buy has been somebody else’s. It arrives with history attached, and scoring begins on your first day of dialing rather than after some grace period.
Why rotating to fresh numbers doesn’t help
Number-hopping is what most shops do and it is the wrong answer. The instinct is understandable. One number is flagged, so retire it and dial from a clean one.
The problem is that the flag was earned by a pattern. Move the pattern to a new number and it reproduces there. Now you have two damaged numbers instead of one. The footprint also looks more like a spam operation than it did before.
There is a second problem. The replacement is rarely clean. Most numbers already carry a flag when a lender gets them. A swap without a change in behavior buys days, not a fix.
There is one case where replacement is the only option. A number carrying a regulatory block cannot be remediated. Those get replaced, and nothing else does.
Registration is the floor, not the fix
Register your numbers. Then stop expecting it to be enough, because registration establishes a baseline and does not override behavioral scoring.
The same goes for the paid layer above it. Branded caller ID for mortgage lenders puts your name and logo on the screen. It buys recognition, not immunity.
Registration and remediation are the two mechanical halves. The behavioral half belongs to you, and no vendor can register their way out of a dialing pattern. Call duration, answer rate, volume per number and complaint rate are the inputs the model watches. If those do not change, the flag comes back.
Registration also has a lead time, and it depends on people outside your project. It belongs with the other setup work you start early rather than finish late. That is one of several things worth settling in what to decide before you go live.
There is no regulator to appeal to
Blocking and labeling are treated completely differently, and almost nobody outside telecom knows it.
If a provider blocks your call using analytics, federal rules apply. The FCC requires providers to return SIP code 603+, so you learn that the block happened and why. Providers that block must also offer a single point of contact for disputes. That is a redress path with an address on it.
A labeled call is not blocked. It rings. It shows “Spam Likely” and the borrower declines it. None of the blocking provisions apply, because nothing was blocked.
What exists instead is voluntary. The analytics engines run their own correction processes, and the industry maintains a best-practice framework for handling labeling complaints. Both are real and neither is mandated. That is why remediation runs engine by engine, and why nobody can guarantee a date. You are asking for a correction under a good-faith framework, not filing a claim.
Spam remediation: which lines need it and which do not
Outbound and local-presence numbers need it. Inbound-only numbers do not.
The reason is mechanical rather than economic. An inbound line places no calls, so there is no outbound behavior for an analytics engine to score. Remediating it buys nothing. A loan officer’s dedicated outbound line is scored like any other.
Local presence deserves a warning. It puts a number near the borrower’s area code on the screen. Every one of those numbers is an outbound caller ID, so each needs registration and remediation. Run it for every user or for none, because mixed settings break inbound routing. More numbers is more reputation to manage, not a way around it.
Most shops get the scope wrong in one of two directions. They remediate everything, which spends money on lines that were never at risk. Or they remediate nothing, because the quote covered every number they own and the total looked absurd. Sort your numbers by what they do before you price anything.
Then set expectations on timing. A submitted correction usually clears in about 1 to 5 days, and it varies by engine. Three things decide whether it stays cleared.
- A cleared flag is not a pass. If the same calling pattern trips the algorithms again, the flag comes back.
- Baseline trust only resets with better behavior. Skip the basics and the number never earns its way back to neutral.
- Most numbers start flagged. A team that skips the basics will struggle to clear flags at all.
That sorting runs into a bigger question about where your numbers should live at all. Answering it is part of what a mortgage CRM has to do when it owns your calling.
Why cheap calling platforms underperform
A cheap dialer prices the minutes and skips the work that keeps calls answered. You find out from the connect rate, weeks late.
Here is what usually goes missing.
- No registration. Numbers go live with no baseline at the analytics engines.
- No monitoring. Nobody checks whether a number is flagged until answer rates collapse.
- No remediation. A flagged number stays flagged, or gets swapped, which repeats the problem.
- No per-number visibility. Loan officers dial from a labeled number without knowing it.
- No list hygiene. Dead numbers stay in the queue and produce short calls all day.
The per-minute saving is real. So is the cost of a floor dialing from labeled numbers for a month.
Shape runs those layers inside the CRM. We register client numbers with the carrier analytics engines to set a baseline. Enrolled outbound numbers are checked once a day. Each number shows as Good or Bad, so a loan officer sees a flag before dialing. Remediation is submitted automatically, and numbers in remediation are rechecked every 3 to 5 days. It covers outbound and local-presence numbers. Phone validation checks whether a number works and flags invalid ones so they stay out of the dialer. The full setup is in the spam remediation guide.
None of that replaces the behavior. It tells you where you stand and fixes what can be fixed.
What a lender actually runs
Caller reputation for mortgage lenders is standing work, not a project. Four things, and only the first has an end date.
Somebody owns it. Name a person. Caller reputation sits between marketing, operations and IT. In most shops that means it sits nowhere until answer rates collapse.
Monitoring runs on a schedule, not on a complaint. Checking when somebody notices is how a slide becomes a crisis. The useful signal is direction rather than a single reading.
Number inventory is documented. Which numbers exist, what each one does, which are registered, which are flagged. Most lenders cannot produce this list, which is why the first remediation quote is always wrong.
Entity changes trigger a full pass. When a lender rebrands or gets acquired, carrier registration, CNAM records and brand records move to the new entity. Numbers keep dialing in the meantime under a name that no longer matches the registration. That mismatch is what the scoring models look for. Carrier registration is one item on a longer list. What else moves when the entity name changes covers the rest.
None of that requires a new platform. It requires somebody with the list, and a calendar. It also requires a CRM for mortgage lenders that records call duration and outcome at the number level. Those are the inputs you are scored on.
Widely shared figures on answer rates, branded calling, flagged numbers and safe daily call counts are left out. None traces to a study.
Frequently asked questions
Why are our connect rates dropping when we are dialing more?+
Because more volume per number feeds the spam score. Declined calls, short calls and repeat dials tell the analytics engines your calls are unwanted. The number gets labeled, more borrowers decline, and the score drops again. Steady daily volume, clean lists and registered numbers break the loop. More dials make it worse.
Why do our calls show as spam likely when we are STIR/SHAKEN verified?+
Because those answer different questions. STIR/SHAKEN signs the call so a carrier can verify the number is not spoofed. Spam labeling is a separate scoring model. It looks at how your traffic behaves: answer rates, call duration, complaints. A fully verified call from a legitimate business can still be scored as a nuisance. Verification gives no protection from that.
Will branded caller ID stop our numbers being flagged?+
No. Branded caller ID puts your name and logo on supported handsets, which raises the chance someone answers. It does not touch the analytics score that produces the label. The two run independently, so a branded call can still arrive marked. Branding is worth buying for what it does, not for what vendors imply it prevents.
Should we rotate numbers when one gets flagged?+
Only when the number carries a regulatory block, which cannot be remediated. Otherwise rotation makes things worse. The flag was earned by a calling pattern, and the pattern moves to the new number. Most replacement numbers arrive flagged already. Fix the behavior and remediate the number you have.
How long does spam remediation take?+
A submitted correction usually clears in about 1 to 5 days, varying by analytics engine, with no guaranteed date. Clearing is not permanent. If the same calling pattern trips the algorithms again, the flag returns. Remediation holds only when volume, call duration and list quality change with it.