Recruiting conversations spend all their technology time on one question, which is what platform the producer will be on.
That is rarely the expensive part. The expensive part is everything those systems render, and the reason nobody plans for it is that no system moved. A branch transition checklist that only lists platforms will miss the work that actually takes three months.
Three kinds of move happen in this business, and only one of them is a systems project.
Three kinds of move, and only one is a systems project
Work out which one you are doing before anyone opens a project plan.
The move
What changes
What it actually costs
Producer brings their own DBA
The corporate entity underneath
Low. Brand survives, registrations move
Full corporate rebrand
Everything the systems render
High, and nobody budgets it
Platform change
The systems and the workflow
Highest, and it is a retention risk
The first is the cleanest. A producer operating under their own DBA keeps their name, their logo and their marketing. What changes sits underneath: the legal entity, NMLS numbers, compliance footers, the sending domain, the identity on carrier registration.
The second is where teams get caught, and it gets its own section below.
The third is a different kind of project and it is the one most likely to cost you the producer. Which platform they land on is worth deciding carefully. That decision has a shorter version in the platforms loan officers actually run.
The case that looks free and is not
Where the brand changes and the systems do not, nobody opens a project. That is precisely why it drags.
No system moved, so there is no migration, no cutover and no owner. What there is instead is every surface the technology renders, still carrying a name that no longer exists.
Work the list.
Email templates and signatures across every user
Automated campaign content, including sequences already running
Borrower portal branding and any co-branded landing pages
Pre-approval letters and document templates
Flyers, one-pagers and rate sheets already in agents’ hands
QR codes printed on material you cannot recall
Review profiles, directory listings and social accounts
Anything a borrower received last month with the old logo on it
Two of those are worse than the rest. Printed material in circulation cannot be updated. A redirect from the old URL is the only fix, and somebody has to remember to build it. And campaigns already in flight keep sending old branding until somebody edits each one. That is a per-sequence job rather than a settings change.
Changing CRM brand settings gets you the header and the footer. It does not get you the content inside a template somebody wrote two years ago.
What moves with the entity rather than the brand
Some things are attached to the legal entity, and they move whether or not the logo changes.
NMLS numbers appear in more places than anyone remembers. Email footers, landing pages, social profiles, printed material, ad accounts. Compliance footers and disclosure language travel with them.
The sending domain is the one with a dependency outside your team. A new domain needs its authentication records added by whoever controls DNS. Until that is done, campaign mail lands in spam.
Carrier registration is the one people miss entirely. Every outbound number carries a business identity on file with the carrier analytics engines. That identity is the entity you just changed. Leave it alone and your calls go out under a name the record does not recognize. Scoring picks that up. If numbers already carried problems, what happens to a flagged number covers why replacing them is the wrong instinct.
When a producer keeps their own CRM
Two things decide this, and only the first is about software.
Do they own the account. An individually held account travels with the person. Their contract, their data, their configuration. A seat on a corporate account does not travel, and no negotiation changes that. Which one applies is a property of the platform, and it is checkable before a conversation starts.
Will you allow it. Shops sit in three places here. Some let officers choose their own CRM from the outset. Some require the corporate platform for everyone. And plenty of the second group make exceptions for top producers, which is where the negotiation actually happens.
So this is rarely a flat yes or no. Ownership decides whether they can bring it. Your policy decides whether they may use it. Both have to line up.
What they are protecting is the workflow, not the software. Years of pipeline stages, triggers, templates and follow-up cadence tuned to how they actually sell. None of that ports. A producer moving onto a corporate platform does not lose a CRM. They lose a system of work, and they rebuild it while trying to hold production up.
That is the real cost of a platform change, and it is not the one that gets discussed. The license fee is visible. A quarter of degraded production is not, until it shows up in the numbers.
What the receiving shop should work through, none of which is about generosity.
What an account outside the corporate instance means for pipeline reporting
Whether compliance can see the outreach
How leads route to somebody who is not in the corporate system
What happens to the database if that producer moves again
The last one is the question nobody asks while it is still cheap to answer.
Where the platform does change, sequence for it. Move the pipeline first and leave the cadence alone until the system has earned some trust. A producer who loses both at once underperforms for a quarter, and some of them leave. A loan officer CRM system that lets someone rebuild stages and triggers without a support ticket shortens that quarter.
The branch transition checklist items with a clock on them
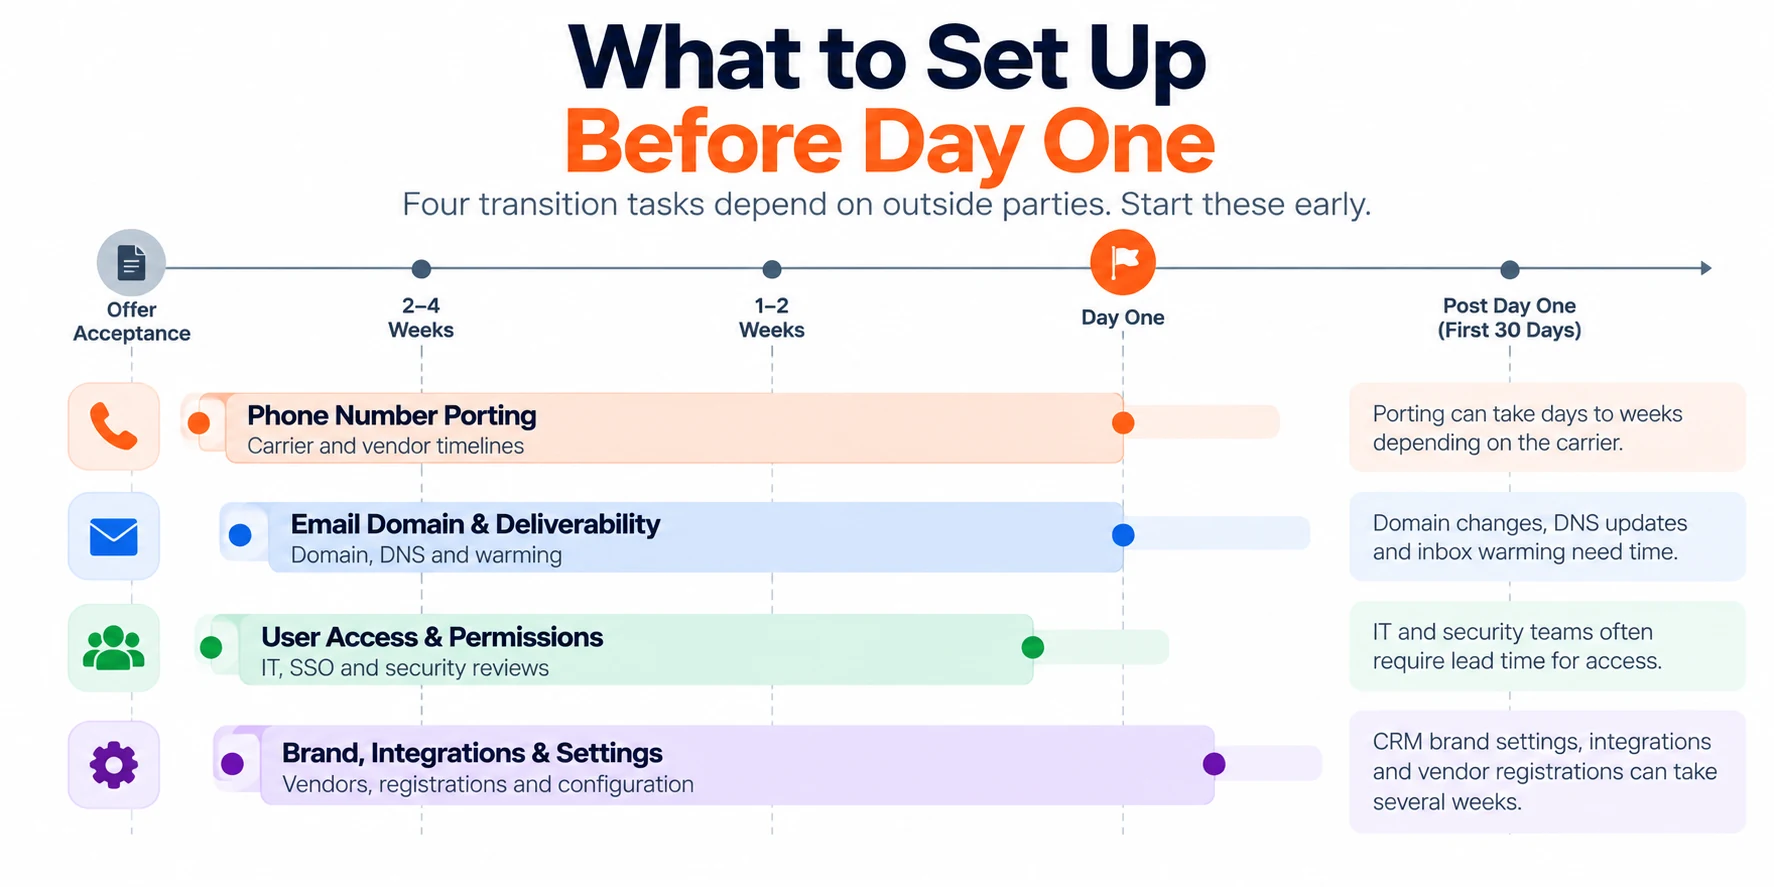
Four things depend on somebody outside the transition, which makes them the ones to start first.
Email domain authentication. DNS records have to be added by whoever controls the domain, and that is often not your team. Start it the week the offer is accepted.
Carrier registration under the new entity. Registration is not instant and the numbers keep dialing while it is pending.
Lead-source posting URLs. Every purchased source posts to an endpoint. Repointing one means a ticket with that vendor, on their timeline. Leads keep arriving at the old destination until it is done.
Seat provisioning. In a branch network this is an HR step before it is a software step. It has a longer tail than anyone plans for.
The ordering principle matters more than the list. Identifiers first, then the systems that reference them, then the material that renders from those systems. Change them in the wrong order and links break in ways that are hard to trace. Getting that sequence right is the same discipline as implementing a mortgage CRM from a standing start.
What to check thirty days after
Four things fail silently, which means nobody reports them.
Campaign mail landing in spam under a sending domain that was authenticated late. Calls showing a spam label because registration and entity no longer match. Old QR codes and printed material still pointing at a URL that returns nothing. And review profiles, directory listings and map results still carrying the previous name. That is usually the last thing anyone gets to, and the first thing a borrower sees.
Put a date in the calendar at the start of the transition. Thirty days is long enough for the problems to surface and short enough to fix them before anyone outside notices.
Frequently asked questions
Can a loan officer keep their CRM when they change companies?+It depends on two things. First, whether the account is theirs, meaning their contract and their data rather than a seat on a corporate account. A seat does not travel. Second, whether the receiving lender allows it. Some let officers choose their own CRM. Others require the corporate platform, and even there, top producers often negotiate an exception.
What happens to our phone numbers when the entity name changes?+The numbers keep working and their registration goes stale. Each number carries a business identity on file, and that identity is the entity you just changed. The call and the record stop agreeing. Update the registration as part of the transition rather than after it. Scoring runs continuously, and the mismatch is one of the things it looks at.
How long does a branch transition take?+The systems work is usually weeks. What extends it is anything depending on somebody outside the transition. DNS changes, carrier registration, lead-vendor endpoints and seat provisioning. Start those four the week the offer is accepted and the rest compresses around them.
Do we have to move loans in process?+Usually no, and mixing the rule is worse than either answer. Let in-flight files finish where they started while new business opens in the new system. Or move everything on a set date. What loses files is leaving people to guess which system holds which loan.
What should I consider before moving my branch to another lender?+Plenty goes into a branch move, and much of it is financial: comp, splits, and the economics of the deal. This page covers the technology and operations side, which is easy to underestimate. A few considerations that belong on the list: which kind of move it is (keeping your own brand, adopting the new lender’s, or changing platforms); the tasks that depend on outside parties and set your timeline (email domain authentication, carrier registration for your numbers, lead-source posting URLs, and seat provisioning); and what travels with the legal entity, like NMLS numbers and compliance footers. Then recheck about thirty days later, because the things that break tend to break quietly.
Kevin Benner is the Chief Revenue Officer at Shape Software, where he leads revenue, marketing, and customer growth. He brings over 23 years of experience in mortgage lead generation and sales technology.
Mortgage texting software is judged by what happens after the borrower replies, not by how many texts it can send. Any tool can send. The ones worth paying for put the reply on the borrower’s record and stop the automation. Then they show a loan officer who needs an answer. Everything else is a bulk […]
Most lenders reading about the Encompass SDK transition deadline have nothing to migrate. That is not what the coverage suggests. The subject has produced a steady run of posts about an Encompass SDK sunset, an end-of-life, a cutover. Several carry a countdown clock. Some of it is written by firms that sell migration work. Here […]
Most lists of the best CRM for banks and credit unions are general mortgage CRM lists. Each entry gets a sentence about members added to it. That misses what actually separates these platforms for a depository. Your mortgage division runs like any mortgage shop, so the mortgage capability has to be real. But you also […]