Choosing Social Media Approval Software for Loan Officers
Social media approval software for loan officers decides one thing: whether compliance sees a post before the public does. Every product in this category answers that question one of two ways. Some stop a post until someone approves it. Others find posts after they go live and flag the problems. Pick the wrong kind, and you pay for coverage you thought you had.
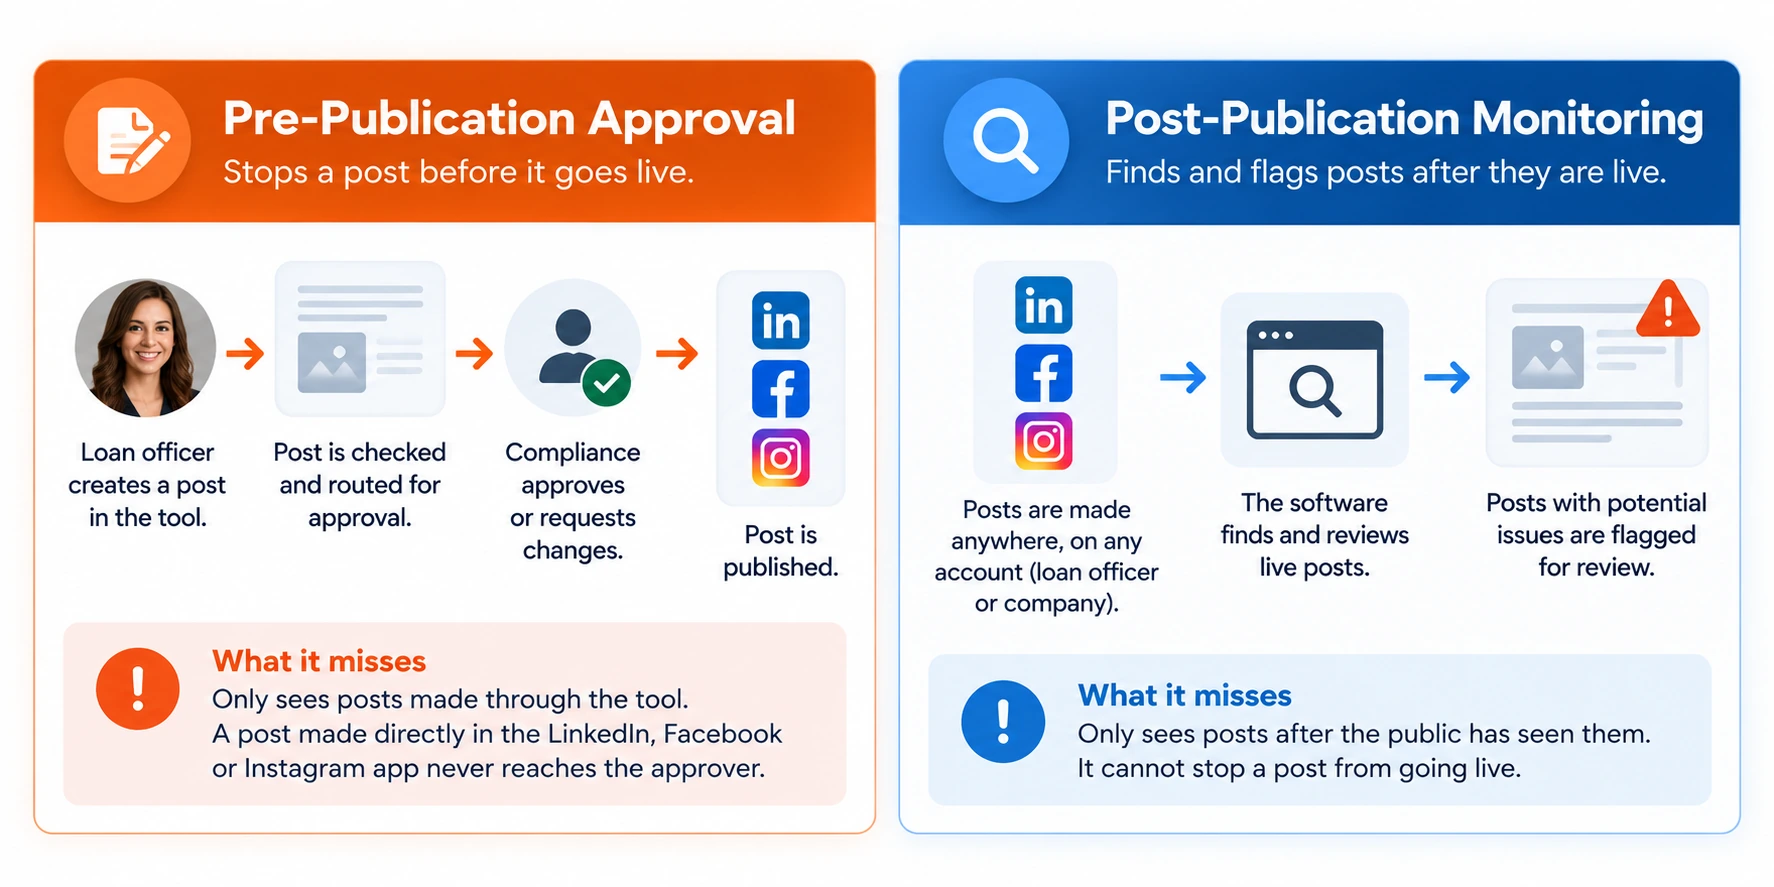
Approve before posting, or monitor after
Pre-publication approval puts a review step between the loan officer and the post. Warrant describes its product this way: posts are checked against regulations and company policy, routed for approval, then published. Shape’s CRM works the same way at the point that matters. A loan officer cannot send a social post until it clears a compliance check.
Post-publication monitoring watches what is already live. ActiveComply says it finds loan officer and company accounts automatically and pulls them in for review. PerformLine monitors and scores posts against regulatory rulebooks. Comergence, part of Optimal Blue, evaluates activity across loan officers and channels on a schedule.
Each kind has a blind spot. An approval tool only sees posts made through the tool. A post a loan officer types straight into the LinkedIn app never reaches the approver. That limit applies to every approval product, Shape included. Monitoring catches posts made anywhere, but only after the public has seen them.
Most lenders with more than a handful of loan officers end up needing both. Approval for planned content, monitoring for everything else.
Why lenders need a review step at all
Regulators treat social media as another channel, not a separate world. The FFIEC’s 2013 guidance applies to banks, credit unions and nonbanks the CFPB supervises. It expects a risk management program for social media, including policies, monitoring and oversight of third parties.
A loan officer’s post about rates or programs is advertising. The same disclosure rules that apply to a flyer may apply to the post. Social posts are not calls or texts, so they sit outside TCPA compliance for mortgage lenders. The advertising rules are what matter here. How they apply to a given post is a question for your counsel.
What social media compliance software has to do
Any social media compliance software worth a demo should handle six jobs:
- Route to a named approver. Every post goes to a person, with a backup when that person is out.
- Keep an audit trail. Who wrote the post, who approved it, what changed and when.
- Attach required details. The NMLS ID and any disclosures, added automatically rather than remembered.
- Flag risky language. Rates, payments and “lowest” claims should stop for a closer look.
- Publish where loan officers actually post. LinkedIn, Facebook and Instagram at minimum.
- Return rejected posts with a reason. A rejection without feedback teaches nothing and stalls the next post.
Ask each vendor to show a post that gets rejected, fixed and approved. A feature list cannot show you that loop. We run the same test on every platform in our mortgage CRM comparison.
Approving loan officer social posts without killing the habit
The hardest part of approving loan officer social posts is speed. If approval takes three days, a post about this week’s market goes out next week, or not at all. Loan officers stop posting, and the compliance problem solves itself in the worst way.
Three habits keep posts moving. Build a library of pre-approved posts loan officers can publish as written. Set an approval turnaround and hold the approver to it. Approve templates once, so a loan officer only needs review when they change the substance.
Archiving is a separate question. Your charter and regulators decide whether your brokerage needs social media archiving. Check whether the approval tool covers it.
Social media monitoring for loan officers: when you need it too
Approval covers what goes through the system. Social media monitoring for loan officers covers the rest. That includes personal accounts and old posts written before the policy. It also includes comments under other people’s posts.
Monitoring also catches the details that drift. A loan officer changes their profile, drops the NMLS ID, or moves states. Knowing where NMLS numbers must appear in ads is the start. Checking that they still appear is the job monitoring does.
Social media approval software for loan officers inside the CRM
Built into the CRM, social media approval software for loan officers keeps posts, approvals and contacts in one system. In Shape, the Social Media Manager routes posts through an approval workflow before they publish. It keeps a shared library of approved posts, and pulls comments and messages into one inbox. It publishes to LinkedIn profiles and company pages, Facebook, Instagram and several other networks.
Approval belongs in the evaluation of a mortgage CRM with compliance features and audit trails. It is not only a separate compliance purchase.
Frequently asked questions
Do loan officers’ personal social accounts need compliance approval?+
It depends on your policy and on what the account is used for. A personal account that advertises loans or rates may be treated like any other advertising channel. Many lenders cover it with monitoring rather than approval. Your counsel should set where that line sits for your shop.
Who should approve loan officer social posts?+
Usually compliance or marketing, with one named backup. The approver needs authority to say no and the time to answer quickly. A slow approver kills posting faster than a strict one. Set a turnaround target and measure it.