Mortgage Texting Software: What Lenders Should Require
Mortgage texting software is judged by what happens after the borrower replies, not by how many texts it can send. Any tool can send. The ones worth paying for put the reply on the borrower’s record and stop the automation. Then they show a loan officer who needs an answer. Everything else is a bulk sender.
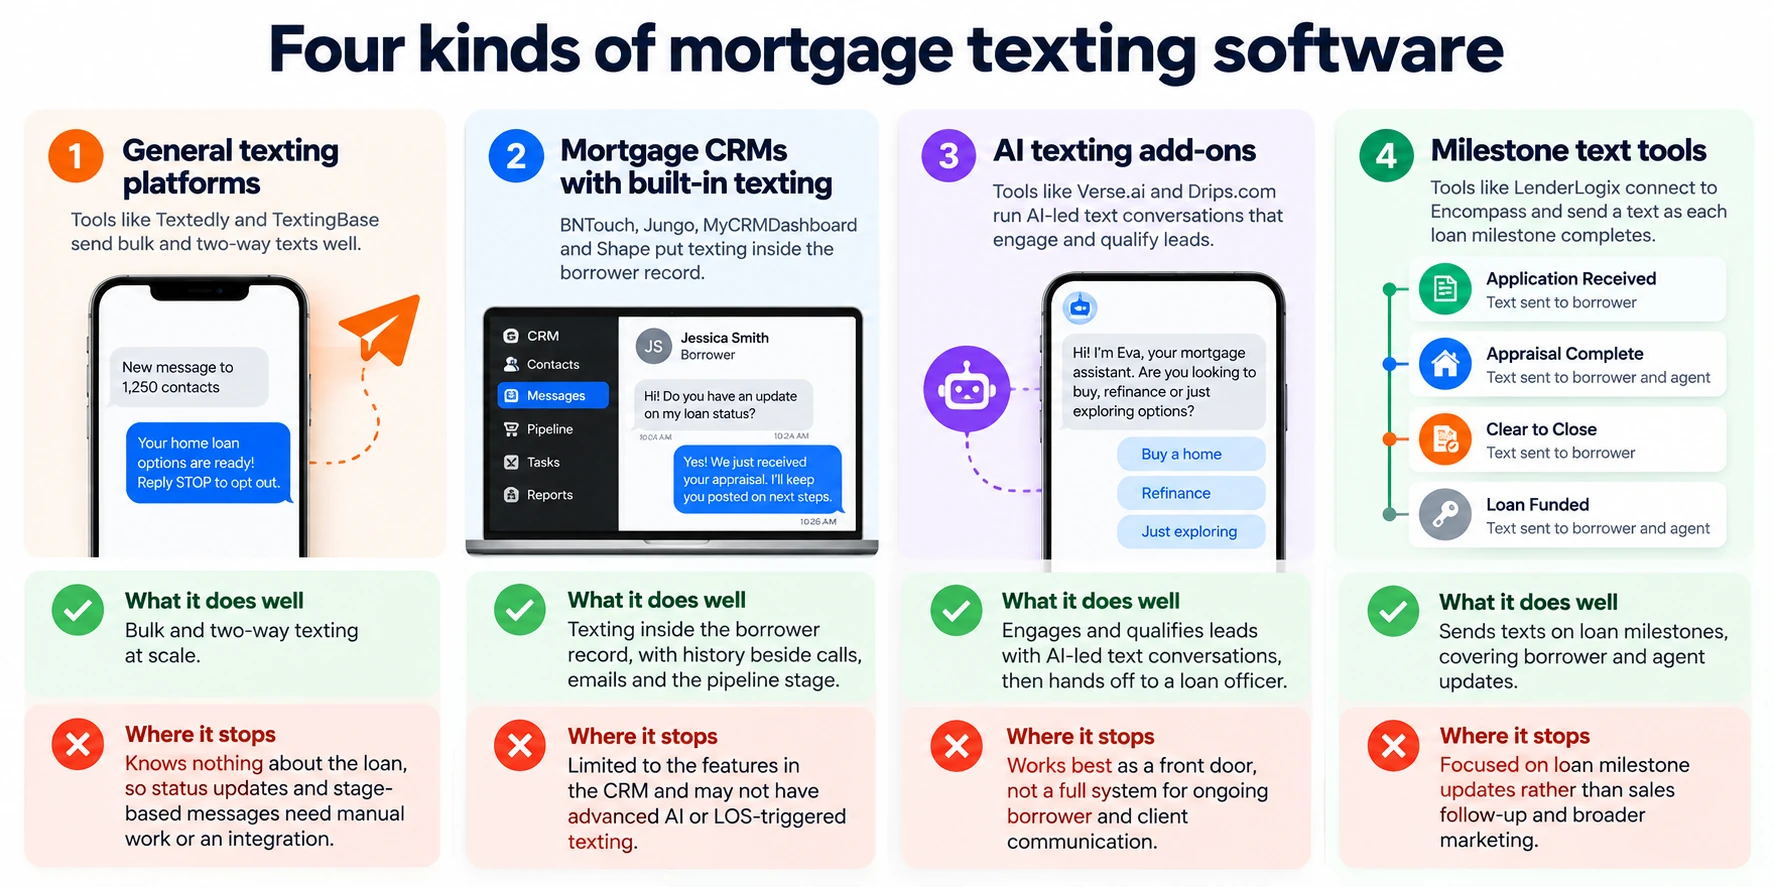
Four kinds of mortgage texting software
Lenders shopping for texting end up comparing four different products.
- General texting platforms. Tools like Textedly and TextingBase send bulk and two-way texts well. They know nothing about the loan, so status updates and stage-based messages need manual work or an integration.
- Mortgage CRMs with built-in texting. Many industry specific CRMs including Shape, BNTouch, Jungo, and Bonzo put texting inside the borrower record. The text history sits beside calls, emails and the pipeline stage.
- AI texting add-ons. Tools like Verse.ai and Drips.com run AI-led text conversations that engage and qualify leads. Then they hand off to a loan officer. They work best as a front door, not a full system.
- Milestone text tools. LenderLogix connects to Encompass and sends a text as each loan milestone completes. It covers borrower and agent updates rather than sales follow-up.
Most lenders need texting in the CRM, plus one specialist tool at most. Running three texting products means three opt-out lists and three places a reply can hide.
Four ways a text gets sent
Every texting tool has to handle four kinds of send, and each one breaks in its own way.
- Manual sends. A loan officer texts one borrower. The risk is a text that never reaches the record.
- Bulk sends. One message goes to a list. Carriers watch the volume, and consent carries the most weight here.
- Drip campaigns. A sequence runs on a schedule. The risk is a drip that keeps sending after the borrower replies.
- Triggered sends. An event fires the text, such as a loan milestone or a form fill. The risk is a trigger firing at 10 p.m., or to someone who opted out.
Ask a vendor to show all four. The three automated types should only go out during allowable hours. A tool strong on bulk and weak on triggers pushes your team back to their phones.
Eight things mortgage texting software should do
Treat these as requirements, not features to admire in a demo. Any mortgage CRM buyer’s guide worth reading checks for them:
- Help you register. Unregistered business numbers get filtered by carriers. Ask who handles 10DLC registration and how long approval takes.
- Honor an opt-out everywhere. A borrower who texts STOP should never hear from another loan officer or another number on your account.
- Respect quiet hours. A compliant system holds every automated text, from drips, triggers and bulk sends, to allowable hours. Shape enforces texting quiet hours.
- Keep the conversation on the record. Every text, in and out, belongs beside the calls and notes on that borrower.
- Show who sent what. A loan officer replying should see whether the last text came from a colleague or from automation.
- Stop the drip when the borrower replies. A reply is a conversation. Automation that keeps sending looks careless.
- Send on loan events. A milestone change in the LOS should be able to trigger the next text.
- Report failures. Failed texts should show up in a report, with a reason, before anyone wonders why a borrower went quiet.
SMS for mortgage brokers: what keeps texts delivering
Delivery is the part buyers forget to ask about. Carriers judge the number, the message and the volume. Texts that look like spam get filtered whatever the software promises.
Ask how the tool paces bulk sends. Shape queues large sends rather than firing them at once, which carriers treat more kindly. Ask what happens to a message with flagged content. Shape stops it before it sends and asks for a rewrite. Ask how the tool handles a number that is not registered. Your text message cadence decides the rest.
Texting software for mortgage brokers that knows the loan
The value of texting inside a CRM shows up after the application. In Shape, a milestone change in the LOS can trigger a drip that includes texts, through the LOS integration. The borrower hears that the file moved to underwriting without anyone remembering to send it.
Shape’s texting guide covers the rest of the workflow. That includes an inbox of replies waiting for an answer and the sender shown on every text. It also shows the number each borrower replied to. Opt-out keywords such as STOP and UNSUBSCRIBE are handled automatically.
The limit applies to every CRM-native tool, Shape included. A text sent from a loan officer’s own phone never reaches the record. The software cannot settle whether loan officers can text from personal phones at all. That is a policy question for the lender.
SMS marketing for mortgage lenders: where compliance sits
SMS marketing for mortgage lenders runs under rules that may differ from email. Consent, quiet hours and opt-out handling are the usual pressure points. How those rules apply to your program is a question for your counsel.
The software’s job is narrower. It should make the compliant path the default and the risky path hard. Look for consent stored on the record, opt-outs applied account-wide, and automated sends held to permitted hours.
How to test texting software in a demo
Run four tests before you sign:
- Text STOP to a demo number, then try to send from another user.
- Reply to an automated text and check whether the drip stops.
- Send a long message with a link and see what the tool flags.
- Ask for the failed-message report and the reason codes in it.
Any vendor confident in its texting will run all four live. That is how you find a mortgage CRM with SMS that does the job.
Frequently asked questions
Is AI texting the same as mortgage texting software?+
No. AI texting answers and qualifies early conversations without a person. Texting software is the system the conversation runs in: the record, the opt-outs, the reporting and the loan officer’s reply. AI texting works as a layer on top. It does not replace the texting system underneath it.
Do bulk texts and one-to-one texts follow different rules?+
They may. A reply to a borrower’s question is a conversation. A bulk marketing text to a list is where consent, quiet hours and opt-outs carry the most weight. Your counsel should set where that line sits for your program.