What Triggers a “Trigger Term” Disclosure in a Rate Ad?
Trigger term disclosures are owed the moment an ad states any of four things. The amount or percentage of a down payment. The number of payments or period of repayment. The amount of any payment. The amount of any finance charge.
State one and you owe three more disclosures. Those are the Regulation Z trigger terms, and the rate advertising disclosure rules sit in the same section, 1026.24. One of the four carries a definition problem no guide raises.
What Trigger Term Disclosures Require
Three things, in the same ad, clearly and conspicuously. The down payment amount or percentage. The terms of repayment across the full loan, including any balloon. And the APR, using that term.
The Down Payment Trigger Has a Definition Problem
Trigger terms in mortgage ads carry a wrinkle the guides skip.
Regulation Z defines down payment at 1026.2(a)(18). It is an amount paid to a seller in a credit sale. A credit sale is defined at 1026.2(a)(16) as a sale where the seller is the creditor.
The CFPB’s Official Interpretation carries that through. Comment 24(d)(1)-1.i states the trigger is limited to credit sale transactions.
Read literally, that describes a builder financing its own inventory, or a dealer carrying the paper. It is harder to read it as covering a broker originating a loan on someone else’s house.
We are not going to tell you what that means for your ads. Shape builds CRM software and is not your counsel. We could not find an examiner finding showing how this is treated in practice. The text says one thing. What happens on exam is another.
The Question Worth Asking
Take this one to your compliance officer, in these words.
Does our down payment language trigger 1026.24(d)(2), given how 1026.2(a)(18) defines down payment?
That is narrower than “are we compliant,” which makes it answerable.
It rarely changes the ad either way. An ad saying “3.5% down” almost always says “30-year” or quotes a monthly payment. Both trigger on their own.
Regulation N Governs What Regulation Z Misses
Here is what no competing page on this subject mentions.
The Mortgage Acts and Practices Advertising Rule, Regulation N, bars material misrepresentations in mortgage advertising. The FTC and the CFPB share enforcement over non-bank mortgage advertisers.
That makes it a records problem too. Proving what ran and who approved it is the job of a mortgage CRM with compliance features and audit trails.
Regulation N does not work through triggering terms. It works through whether the claim misleads. A down payment figure you cannot deliver is still a problem, by a different route, with civil penalties.
Escaping a Reg Z trigger is not permission. It moves which rule you answer to.
Rate superlatives hit the same wall. Our post on whether you can advertise a lowest-rate claim covers the substantiation problem.
What Does Not Trigger
Vague language does not trip the rule. “Low down payment” is fine. So is “affordable monthly payments.” The commentary names “monthly payment terms arranged” and “take years to repay” as not triggering.
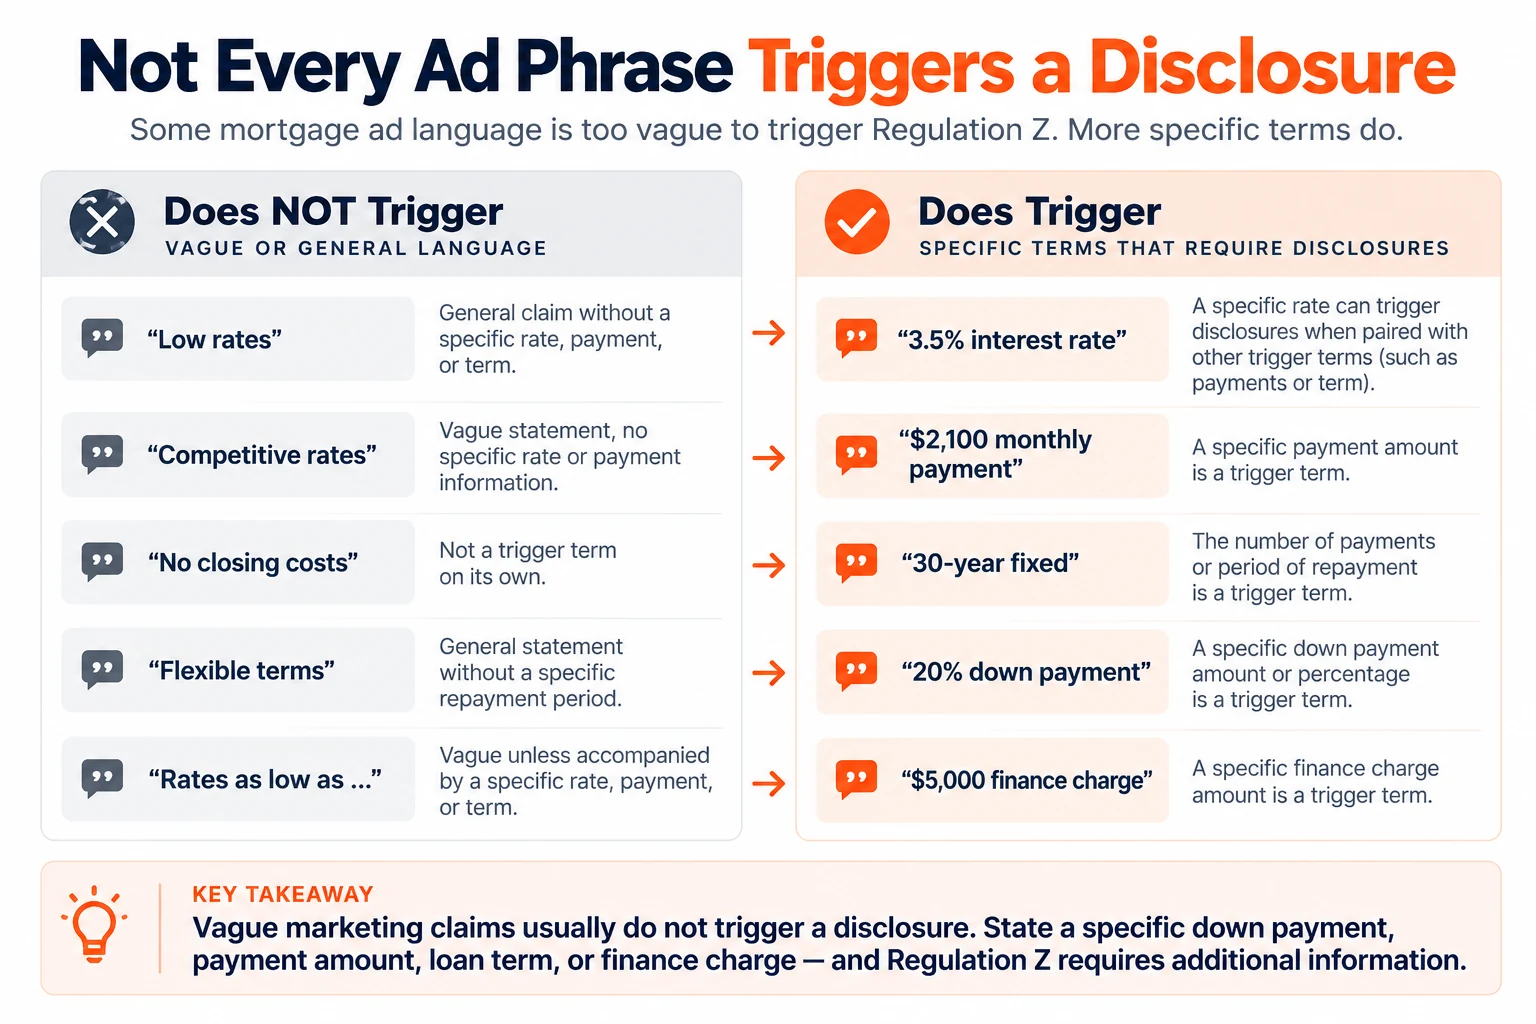
Numbers are what trip it. The moment vague becomes specific, you owe the three disclosures.
Disclosure duties do not stop at Regulation Z. Our post on where your NMLS number has to appear covers the placement rule.
Advertising rules are half of outreach compliance. The rules on calling and texting leads covers what happens after the ad works.
Both get easier on a system that logs every send. The mortgage CRM decision compares platforms on what they record.
This is Shape’s operating read, not legal advice. Take it to your compliance team. State advertising rules add their own requirements and this is written against the federal floor.
Frequently Asked Questions
Is “3.5% down” a trigger term in a mortgage ad?+
Unsettled, and worth asking your compliance officer. Comment 24(d)(1)-1.i limits the down payment trigger to credit sale transactions. Whether that reaches an origination ad is the open question.
In practice it rarely matters, because “30-year” triggers on its own.
Does advertising an APR require additional disclosures?+
No. The APR is not a triggering term under 1026.24(d)(1). Stating it alone requires nothing further.
If the ad also states a payment amount, a repayment period or a finance charge, the three disclosures are owed.
What has to appear once a trigger term is used?+
Three items, in the same ad, clearly and conspicuously. The down payment amount or percentage. The terms of repayment over the full loan, including any balloon. And the annual percentage rate, using that term.